by Michael Jiang Suo | Oct 16, 2026 | Uncategorized
The real estate market continues to change as buyers, sellers, and homeowners respond to economic conditions, housing costs, and evolving lifestyle preferences. In 2026, affordability, mortgage rates, housing inventory, and energy-efficient features remain important factors in real estate decisions.
Understanding these housing market trends can help buyers plan their purchases, sellers set realistic expectations, and homeowners make informed improvements.
1. Housing Affordability Shapes Buyer Decisions
Housing affordability remains an important consideration for buyers. Beyond the listing price, buyers must account for mortgage payments, property taxes, insurance, utilities, and maintenance expenses.
Many buyers are comparing more properties, adjusting budgets, and carefully evaluating their options. Sellers can respond by pricing homes realistically and presenting their properties effectively. Local market conditions are essential because affordability varies by location.
2. Mortgage Rates Influence Purchasing Power
Mortgage rates affect monthly payments and the overall cost of financing a home. Understanding available loan options and getting preapproved can help buyers establish a practical budget before beginning their search.
Sellers should also consider how borrowing costs may affect buyer demand and negotiations. Monitoring current lending conditions can help both parties make better-informed decisions.
3. Housing Inventory Creates New Opportunities
Housing inventory influences competition, property choices, and pricing. When more homes are available, buyers may have additional options to compare. Limited inventory can create stronger competition for certain properties.
Reviewing recent sales, active listings, and local pricing trends can help buyers and sellers understand their market. National headlines offer useful context, but local housing data provides a more accurate picture of individual communities.
4. Technology Is Transforming Real Estate
Digital tools continue to make buying and selling property more convenient. Virtual tours, online property searches, electronic signatures, and digital mortgage applications help streamline the process.
Artificial intelligence is also being used to support property searches and marketing. However, buyers and sellers should verify important details and rely on accurate information when making significant decisions.
5. Energy-Efficient Homes Attract Attention
Energy efficiency is becoming an important consideration for homeowners seeking to manage utility expenses and improve comfort. Insulation, efficient windows, modern HVAC systems, and energy-saving appliances can help reduce energy use.
Before investing in upgrades, homeowners should compare installation costs with potential savings. The value of these features depends on the property, local market, and buyer preferences.
6. Flexible Living Spaces Remain Valuable
Buyers may appreciate homes with adaptable spaces that can serve as work areas, guest rooms, or hobby rooms. Practical layouts, storage, natural light, and usable outdoor spaces can also improve a property’s appeal.
Sellers can highlight these features through thoughtful staging and clear property descriptions. Simple improvements can help buyers see how a home supports their everyday needs.
7. Local Market Conditions Matter
Real estate trends vary by city and neighborhood. Employment opportunities, transportation, local amenities, property taxes, insurance costs, and housing supply can all influence property demand.
Buyers and investors should research local conditions rather than relying solely on national trends. Reviewing comparable sales, rental demand, and ongoing expenses can help them evaluate opportunities more realistically.
Final Thoughts
The major real estate trends of 2026 highlight the importance of affordability, financing, inventory, technology, and energy efficiency. Whether you are buying, selling, investing, or maintaining your current home, staying informed can help you plan.
The best real estate decisions begin with reliable information, careful financial planning, and an understanding of local market conditions.
by Michael Jiang Suo | Oct 9, 2026 | Uncategorized
Look at More Than the Listing Price
Whether buying or selling, it is important to understand that a property’s price is influenced by multiple factors.
Recent comparable sales, property condition, location, size, features, inventory, and current market activity can all provide useful context.
Looking at several factors rather than relying on one number can lead to a more complete understanding of the property.
Research Current Market Conditions
Real estate markets can vary significantly by location and property type. National headlines may provide general information, but local data can offer more relevant insight.
Buyers and sellers can review recent sales, available inventory, days on market, pricing trends, and other appropriate local indicators when evaluating current conditions.
Prepare Your Finances
Financial preparation is important whether you are purchasing a property or planning for future ownership costs.
Buyers should understand their financing options and expected housing expenses. Homeowners should also maintain a realistic budget for repairs, maintenance, insurance, taxes, and other ongoing costs.
Good preparation can make unexpected expenses easier to manage.
Pay Attention to Property Condition
A property’s condition can influence both its value and its ongoing costs.
Buyers should carefully evaluate major systems, structural components, appliances, and visible maintenance needs. Sellers can also benefit from addressing reasonable maintenance and presentation issues before putting a property on the market.
The goal is not necessarily to make every possible improvement. Instead, focus on understanding which improvements are practical and relevant to the property.
Keep Good Records
Property-related records can be useful throughout the ownership and selling process.
Documents relating to improvements, repairs, warranties, permits, insurance, and other property matters can help homeowners maintain a clearer history of the property.
Organized records may also make it easier to answer questions during a future sale or transaction.
Think About Long-Term Value
Real estate decisions should not always be based on short-term market changes.
Buyers can consider how a property fits their financial circumstances and longer-term plans. Homeowners can consider maintenance and improvements that support the property’s condition. Sellers can evaluate pricing and preparation based on current market evidence.
A long-term perspective can provide useful context when market conditions change.
Use Reliable Information
Real estate decisions involve financial considerations, so information should come from credible and relevant sources.
Market statistics should be reviewed in context, while financing questions should be discussed with qualified lending professionals. Legal, tax, insurance, and other specialized questions may also require guidance from the appropriate licensed professional.
Reliable information can help replace assumptions with a clearer understanding of the situation.
Keep the Process Focused
Real estate can involve many moving parts, but the decision-making process does not need to be overwhelming.
Start with the property, financial information, market conditions, and goals that are relevant to the decision. Then evaluate each factor carefully rather than relying on a single statistic or headline.
With thoughtful preparation and good information, buyers, sellers, and homeowners can approach real estate decisions with greater clarity.
by Michael Jiang Suo | Oct 6, 2026 | Second Home
The Newport Beach Second-Home Market: Timing and Opportunity
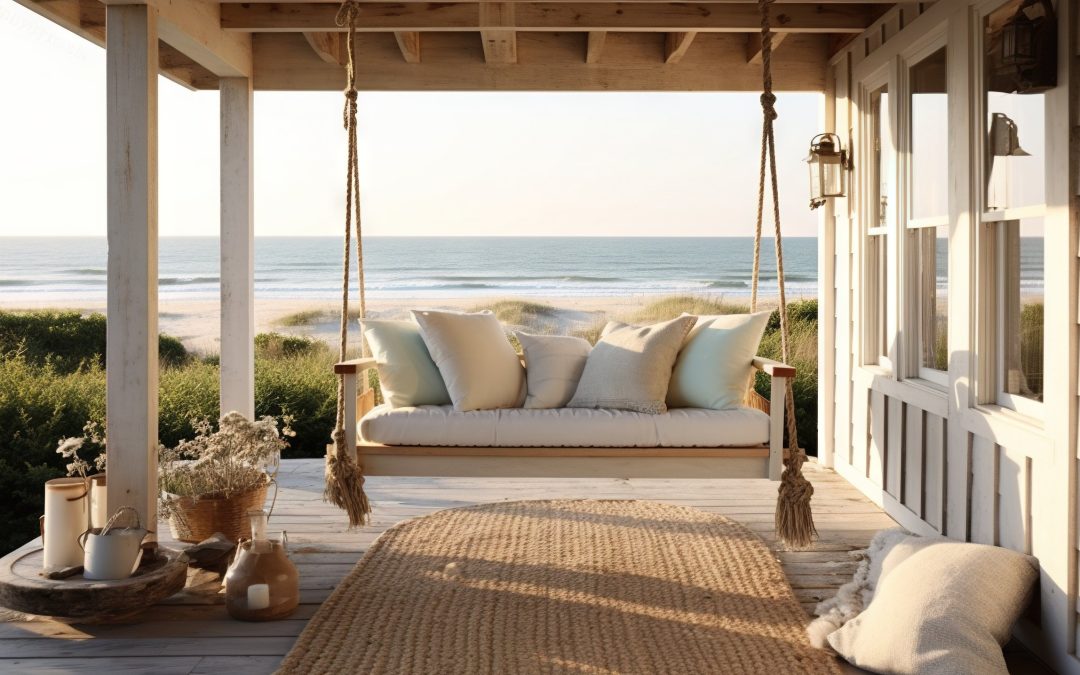
Newport Beach sits along the Orange County coastline where Newport Bay meets the Pacific, and the property market here operates on a different rhythm than the inland SGV communities. Demand runs year-round, but it visibly picks up in spring and through summer, when the harbor, beaches, and waterfront dining draw buyers who want to be close to the action rather than just near it. The peak listing season tends to overlap with peak lifestyle appeal, which compresses timelines and keeps well-positioned properties moving quickly.
The buyer mix is genuinely layered. Some purchasers are establishing a primary residence. Others are acquiring a vacation property they plan to use seasonally, with rental income as a secondary consideration. A third group is focused squarely on investment, drawn by the demand concentration that coastal proximity creates. Short-term rental licensing and coastal zone rules in Newport Beach are specific to the city, so anyone weighing an income-producing strategy needs to verify current municipal requirements before closing, not after.
The sub-areas within Newport Beach vary considerably. Waterfront estates, harbor-front lots, and properties near upscale retail and dining each carry their own price dynamics and buyer profile. PCH connects the city to the broader coastal corridor, giving owners relatively quick access to neighboring beach communities. Sellers in this market benefit from the consistent out-of-area interest, though pricing still needs to reflect current absorption rates rather than the assumption that coastal cachet alone closes deals. A local agent with current MLS data is the right starting point for understanding where a specific property sits in that picture.
- Seasonal demand peaks in spring and summer, aligning with coastal lifestyle appeal
- Buyer types include primary-residence, vacation, and investment purchasers, each with different due-diligence priorities
- Short-term rental licensing and coastal zone rules are city-specific and require municipal-level verification
- Sub-areas such as Balboa Island, Corona del Mar, Newport Coast, and Lido Isle each carry distinct market characteristics
- PCH access connects Newport Beach to the broader Orange County coastal corridor
Waterfront and Coastal Zone Considerations
Newport Beach properties on or near the water carry a distinct set of regulatory layers that don’t apply to most inland transactions. The California Coastal Commission exercises jurisdiction over development and significant alterations within the coastal zone, meaning permits, additions, and even some landscaping changes may require Coastal Commission review on top of standard city approvals. Buyers should confirm whether a specific parcel falls within the coastal zone boundary before assuming what improvements will be permitted after close of escrow.
Short-term rental licensing is another area where due diligence pays off. Newport Beach has its own STR licensing framework, and rules can differ depending on where a property sits within the city, including considerations that apply specifically to the coastal zone. Anyone purchasing with rental income in mind needs to verify current licensing requirements directly with the city before making assumptions about allowable use. Regulations in this area have been subject to change, and what applied to a neighboring property last year may not reflect current policy.
Waterfront and harbor-adjacent properties also tend to carry property-specific disclosures that go beyond California’s standard natural hazard disclosure package. Tidelands easements, dock permits, bulkhead conditions, and marine access rights can all affect how a property is used and what a future owner may be responsible for maintaining. Sellers are well served by assembling this documentation early. For buyers, a thorough review of title, any existing dock or slip agreements, and applicable city and county codes is not optional; it is the foundation of a sound purchase decision in this market.
- Confirm whether the parcel falls within the California Coastal Commission’s jurisdiction before planning any improvements
- Verify Newport Beach STR licensing requirements at the city level; rules vary by location within the city
- Review title for tidelands easements, dock permits, and marine access rights
- Request all existing coastal zone permits and bulkhead or seawall condition records from the seller
- Consult current California disclosure requirements, including natural hazard disclosures, with a licensed professional
Financing, Taxes, and Long-Term Costs
Second-home and investment financing in Newport Beach typically carries stricter requirements than a primary-residence loan. Lenders generally expect larger down payments and may apply higher reserve requirements, so buyers should confirm current guidelines with their lender before making an offer. On the tax side, California’s Prop 13 caps annual increases on assessed value at a modest rate until the property changes hands. At purchase, the assessed value resets to the sale price, and the effective rate is 1% of that figure plus any voter-approved local bonds and assessments layered on top. For a high-value coastal property, that base calculation alone can represent a meaningful annual line item.
Newer developments and planned communities in Newport Beach commonly carry HOA fees that cover shared amenities, landscaping, and exterior maintenance. Those fees vary by community and can shift over time as reserves are drawn down or capital projects are approved. Buyers should request the current HOA financials and reserve study before closing. Short-term rental licensing and coastal zone rules also apply in Newport Beach, so anyone considering rental income as part of the financial picture needs to verify what the city currently permits at the specific parcel level.
Insurance is one of the costs that surprises buyers most often. Coastal proximity can push homeowners insurance premiums higher, and some carriers have reduced their California footprints in recent years, making coverage comparison more important than ever. Flood and windstorm riders may be worth reviewing depending on the property’s exact location and elevation relative to Newport Bay or the Pacific. Maintenance budgets for waterfront or harbor-adjacent properties tend to run higher than inland equivalents, particularly for exterior finishes, decking, and any dock or marine infrastructure. Building those numbers into a realistic ownership model from day one gives buyers a much clearer picture of total cost.
- Second-home loans: confirm down payment and reserve requirements with your lender early in the process
- Prop 13: assessed value resets at purchase; effective rate is 1% of assessed value plus local voter-approved add-ons
- HOA fees: request current financials and reserve study before closing on any planned community property
- STR rules: Newport Beach licensing and coastal zone regulations must be verified at the parcel level
- Insurance: compare carriers and consider whether flood or windstorm coverage fits the property’s location
- Maintenance: waterfront and harbor-adjacent properties often carry higher ongoing upkeep costs than comparable inland homes
Ready to find your dream home in Newport Beach? Contact us today to get started!
by Michael Jiang Suo | Oct 2, 2026 | Uncategorized
Home prices are one of the most visible parts of the housing market, but the number attached to a property does not tell the entire story. Buyers and sellers can benefit from looking at the factors that influence pricing and understanding how local conditions affect property values.
A home’s price can be influenced by location, property condition, size, recent comparable sales, available inventory, buyer demand, and broader economic conditions. These factors can change over time, which is why a property’s value should be considered within its current market context.
Location Can Influence Value
Location remains an important part of residential real estate pricing. Access to transportation, local services, employment centers, parks, shopping areas, and other community amenities can affect how properties are valued.
However, location is only one part of the picture. Two properties in the same general area can have different values because of their size, condition, layout, updates, lot characteristics, and other property-specific factors.
Inventory Can Affect Pricing
The amount of available housing can influence market conditions. When fewer properties are available, buyers may have fewer choices. When inventory increases, buyers may have more opportunities to compare properties and negotiate.
Inventory can also vary by price range and property type. Looking at overall market statistics without considering these differences may provide an incomplete picture.
Comparable Sales Provide Useful Context
Recent comparable sales can help establish a clearer picture of what buyers have actually paid for similar properties. Comparable properties are typically evaluated based on factors such as location, size, condition, features, and timing.
Because no two homes are exactly alike, comparable sales should be considered alongside property-specific characteristics rather than treated as a simple formula.
Market Conditions Can Change
Home prices can move differently from one market to another. National trends may provide useful background, but local supply, demand, economic activity, and housing characteristics can produce different results.
This is why homeowners considering a sale or buyers evaluating a purchase may benefit from looking at current local data rather than relying only on national headlines.
Look at the Complete Housing Picture
Understanding home prices requires more than checking a listing price or a national median. Buyers and sellers can benefit from considering recent sales, inventory, property condition, financing costs, and local market activity together.
A clear understanding of these factors can make it easier to evaluate a property’s asking price and understand how current market conditions may affect a real estate decision.
by Michael Jiang Suo | Sep 25, 2026 | Uncategorized
The economy plays an important role in the real estate market. Changes in inflation, employment, interest rates, consumer confidence, and overall economic activity can influence home prices, borrowing costs, buyer demand, and investment decisions.
Understanding these economic factors can help buyers, sellers, homeowners, and investors better understand changing housing market conditions.
Mortgage Rates and the Economy
Mortgage rates are closely connected to broader financial and economic conditions. Changes in interest rates can affect monthly mortgage payments and the amount buyers can comfortably finance.
For buyers, understanding current financing costs can be more useful than relying on predictions about where rates may go next.
Inflation and Housing Costs
Inflation can affect both the cost of purchasing a home and the ongoing expenses of homeownership. Construction materials, labor, insurance, maintenance, and other services can become more expensive as overall costs rise.
These changes can influence housing affordability and the expenses associated with owning and maintaining a property.
Employment and Housing Demand
Employment conditions can also influence real estate activity. When employment remains stable, consumers may have greater confidence in making major financial commitments. Changes in employment can affect household budgets and housing decisions.
However, economic conditions can vary across markets, so local data remains important when evaluating real estate activity.
Consumer Confidence Matters
Consumer confidence can influence whether people decide to buy, sell, or invest in real estate. When economic uncertainty increases, some consumers may take more time to evaluate their finances before making a major purchase.
As conditions change, buyers and sellers can benefit from focusing on their individual financial circumstances rather than reacting solely to market headlines.
What the Economy Means for Real Estate Investors
Investors often monitor economic indicators when evaluating potential properties. Interest rates, rental demand, operating costs, property values, and broader economic activity can all affect investment decisions.
Careful financial analysis can help investors understand potential income, expenses, and risks before committing to a property.
Looking Ahead
Economic conditions can change throughout the year. No single indicator provides a complete picture of the real estate market, which is why reviewing multiple factors can provide better context.
Final Thoughts
The economy and real estate market are closely connected. Mortgage rates, inflation, employment, consumer confidence, and operating costs can all influence housing activity in different ways.
By staying informed and reviewing current financial and market data, buyers, sellers, homeowners, and investors can make more informed real estate decisions in 2026.
by Michael Jiang Suo | Sep 15, 2026 | Uncategorized
Owning a home is a long-term commitment that involves more than making a monthly mortgage payment. Regular maintenance, thoughtful improvements, and careful financial planning can help protect your property’s condition and value over time.
Whether you have recently purchased a home or have owned one for years, a proactive approach can help you avoid unnecessary expenses and make better decisions about your property.
Stay Ahead of Home Maintenance
Small maintenance problems can become costly repairs when they are ignored. Regularly check your roof, gutters, plumbing, HVAC system, windows, appliances, and exterior areas.
Creating a seasonal maintenance routine can help you identify potential problems early and keep your home operating efficiently.
Understand Your Home’s Value
Home values can change as market conditions shift. Recent comparable sales, inventory, property condition, and improvements can all influence what a home may be worth.
Reviewing your home’s value periodically can be helpful if you are considering refinancing, selling, renovating, or simply tracking your long-term investment.
Make Improvements With Purpose
Home improvements should balance cost, functionality, and potential value. Before starting a major renovation, consider the project’s expected benefits and how much it will cost.
Updates such as fresh paint, improved lighting, updated flooring, kitchen or bathroom improvements, and energy-efficient features can enhance a home’s functionality and appeal.
Keep Homeownership Costs in Mind
The cost of owning a home goes beyond the mortgage. Property taxes, insurance, utilities, maintenance, repairs, and unexpected expenses should all be considered when planning your budget.
Reviewing these costs regularly can help you prepare for future expenses and avoid financial surprises.
Consider Energy Efficiency
Energy-efficient improvements can reduce operating costs while improving comfort. Depending on the home, upgrades such as better insulation, efficient windows, LED lighting, smart thermostats, and updated HVAC equipment may provide long-term benefits.
Before making an investment, compare the upfront cost with potential savings over time.
Keep Important Records Organized
Keep records of major repairs, renovations, warranties, inspections, permits, and service work. Organized documentation can make future maintenance easier and provide useful information when refinancing or selling.
Digital copies can also make important property records easier to access when needed.
Review Your Insurance Coverage
Your home and its contents can change over time, so it is worth reviewing your insurance coverage periodically. Major renovations, new belongings, or changes to the property may affect your coverage needs.
Discuss your policy with your insurance professional to make sure your coverage remains appropriate.
Stay Informed About the Market
Understanding broader real estate trends can help homeowners make more informed financial decisions. Mortgage rates, home prices, inventory, and economic conditions can all influence the housing market.
However, market conditions can change, so avoid making major decisions based on a single headline or short-term trend.
Plan Before Making Major Decisions
Whether you are considering a renovation, refinancing, selling, or simply maintaining your property, start with reliable information.
Compare costs, consider your long-term goals, and seek professional advice when needed. A thoughtful approach can help you make decisions that support both your home and your finances.
Final Thoughts
Successful homeownership is built on consistent maintenance, smart planning, and informed decisions. By taking care of your property, managing expenses, and understanding its value, you can help protect one of your most important assets.
Small steps today can make homeownership easier and more manageable over the years.
by Michael Jiang Suo | Sep 7, 2026 | Mortgage Rates
Are you wondering whether now is the right time to buy a home? With real estate experts predicting rising home prices, it’s natural to feel pressure to act quickly. However, buying a home is a significant financial decision, and it’s essential to consider several factors before making a move. This article will guide you through the key things to think about when deciding whether to purchase a home in today’s market.
1. The Impact of Rising Interest Rates on Home Affordability
Interest rates have a major impact on how affordable homes are. In recent years, interest rates were low, which made mortgages more affordable. But with inflation on the rise, central banks have started increasing interest rates, meaning mortgage rates are going up too.
Higher mortgage rates mean higher monthly payments. Even if home prices are still increasing, rising interest rates could make buying a home more expensive. However, if you’re able to lock in a mortgage rate before they rise further, it could be a good time to buy before rates go even higher.
2. Home Prices Are Likely to Keep Rising
Real estate experts predict that home prices will continue to rise in many parts of the country due to high demand and low inventory. The housing market may be experiencing high prices now, but waiting could mean paying even more later.
However, it’s important to remember that buying at a higher price may not always be the best financial decision if the price doesn’t match the home’s value. Carefully evaluate whether homes are overpriced in your area, and make sure the long-term value of the property justifies the price.
3. Understanding Local Market Conditions
While national trends offer insight into the overall housing market, real estate markets can vary significantly from one location to another. In some cities, prices may be soaring, while other regions may be seeing a slowdown.
To make an informed decision, you need to focus on the housing market in your specific area. Consider local factors such as job growth, population trends, and the potential for future development. Areas experiencing strong economic growth are more likely to see home prices continue rising, while oversupplied markets may stabilize or even see price drops.
4. Assess Your Personal Financial Situation
Before jumping into the homebuying process, evaluate your financial health. Do you have a steady income, a good credit score, and sufficient savings for a down payment? Most lenders require a down payment of 20%, plus closing costs, home inspections, and other expenses.
In addition to the upfront costs, homeownership comes with ongoing expenses such as property taxes, insurance, utilities, and maintenance. Be sure that you can comfortably afford all of these costs in addition to your monthly mortgage payment.
5. The Importance of Long-Term Investment
If you plan to stay in your new home for many years, fluctuations in the market may matter less. Over time, real estate tends to appreciate, and owning a home allows you to build equity. If you’re in it for the long haul, the short-term price increases may be worth it.
However, if you’re considering moving in a few years, you might want to be cautious. Fluctuations in the housing market could impact your ability to sell your home at a profit. If you’re uncertain about your long-term plans, renting might provide more flexibility.
6. Renting as an Alternative
If buying a home doesn’t feel right for you right now, renting is a viable alternative. Renting offers flexibility, especially if you’re unsure about your future or if the market is too competitive. It also gives you time to save for a larger down payment or wait for market conditions to stabilize.
Renting could also be a good option if you’re not ready to commit to homeownership but still want to live in a specific area.
7. The Challenge of Timing the Market
Trying to time the real estate market can be tricky, and even experts can’t always predict what will happen next. The best approach is to focus on your own needs and circumstances. Ask yourself: Do I need a home now? If the answer is yes, then it might be the right time for you to buy, even if prices are rising.
If you’re not in a rush to buy, however, it may be worth waiting for market conditions to change.
Conclusion: Is Now the Right Time to Buy a Home?
Ultimately, the decision to buy a home should be based on your personal situation, not just market trends. While experts predict that home prices will continue to rise, buying a home is a long-term investment that requires careful thought and consideration.
If you are financially ready and plan to stay in your home for years to come, buying now could be a good choice. But if you’re uncertain or if your financial situation isn’t ideal, waiting might be the better option.
In any case, the key to making the right decision is to evaluate your financial stability, the local market conditions, and your long-term goals. Don’t feel pressured to buy just because experts predict rising prices—make sure you’re ready for the responsibility of homeownership.
If you’re ready to start the homebuying process, make sure to consult with a real estate agent to get a better understanding of the local market and find the best home for your needs.
by Michael Jiang Suo | Sep 6, 2026 | DIY
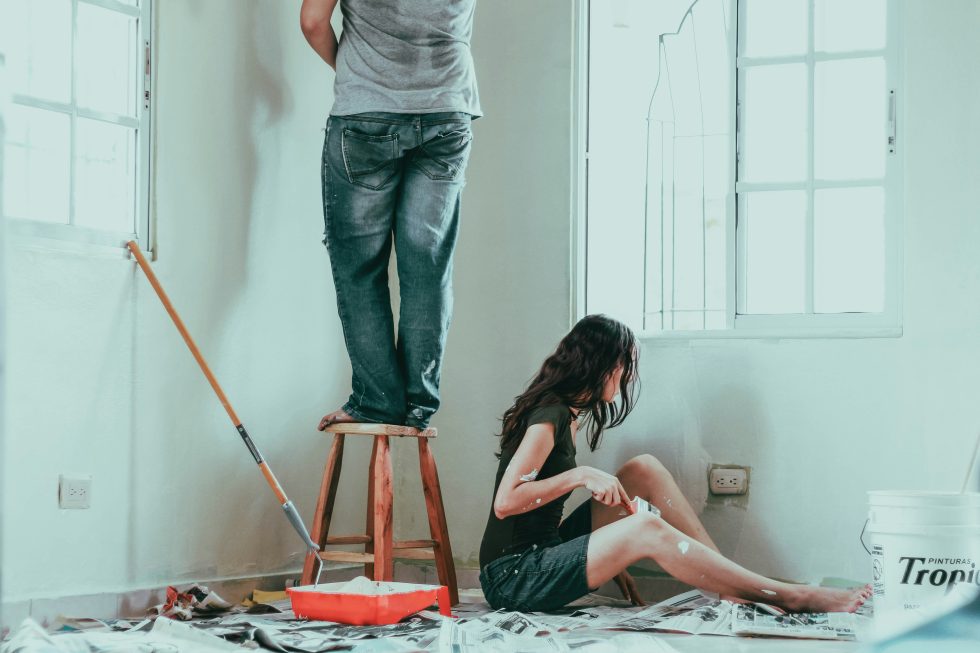
Photo by Roselyn Tirado on Unsplash
From experience, not getting a permit when you need one can be costly. Unpermitted work can lower your property value at the time of sale. No buyer wants to purchase something that may not have been done correctly. Take the advice of a real estate agent and pay the extra for a permit—it will likely pay for itself in the end.
1. Fences
The saying “Good fences make good neighbors” is still true. A well-designed and installed fence can increase privacy and add value to your home. However, make sure to check with the building inspector about the size and type of fence you can install, and get the proper permits. Many towns, cities, and homeowner associations have strict fence height and materials codes. Double-check surveys to avoid building on your neighbor’s property by mistake.
2. Water Heaters
Water heaters might seem like a simple DIY project, but they can be dangerous if not installed correctly. Risks include gas explosions, carbon monoxide poisoning, and electrical fires. All water heater installations require a permit, and it’s recommended to use a licensed plumber.
3. Sheds and Outbuildings
Buying a pre-made shed from a big box store might seem easy, but many states, cities, and counties have specific regulations regarding sheds. It’s best to check these before spending your money, as fines for non-compliance are usually more than the cost of a permit.
4. Garages
Converting a garage into a living space is popular, especially with the rise of Airbnb and the increasing senior population. Whether you want extra space for a home office, spare bedroom, or home gym, you may need permission and a permit from Inspectional Services and the local Housing Authority.
5. Decks
Adding a deck or porch can create a great outdoor living space and add value to your home. However, without a permit, you could face headaches. Structural and safety codes must be adhered to, including railing height and other technical details, which are usually included with your permit.
6. Floor Plans
Changing your home’s layout requires a building permit, such as eliminating a wall or creating a new doorway. This is true even for non-load-bearing walls and small projects like expanding or removing a closet.
7. Windows and Doors
Ready-to-install doors and windows from big box stores might not conform to local building codes. Regulations about ventilation and light determine code standards for window and door frames. Before starting, check if you need a permit and get copies of the building codes.
Checking with your local permit office before starting any DIY project is a good idea. The people who work there are public servants dedicated to ensuring safety in our homes, workplaces, and job sites. Treat them with dignity and respect; you’ll likely receive excellent service.
by Michael Jiang Suo | Sep 6, 2026 | Home Prices
Understanding the value of your home is crucial, whether you’re buying, selling, refinancing, or just tracking your investment. While online estimates or neighborhood comparisons can provide a rough idea, knowing your home’s true market value is key for making informed decisions. Let’s explore why it matters and how to figure out your home’s worth.
Why Knowing Your Home’s Value Matters
1. Set the Right Price When Selling
Pricing your home correctly is critical when selling. If it’s too high, buyers may be turned off; too low, and you might lose money. Knowing your home’s value ensures you set a competitive and fair price.
2. Refinancing Your Mortgage
Lenders need an accurate appraisal of your home’s value when refinancing. Knowing your home’s worth can help you assess whether refinancing is a good option and how much equity you have.
3. Understand Home Equity
Home equity is the difference between your home’s market value and your mortgage balance. Understanding your home’s value helps you know how much equity you’ve built, which can be useful for home equity loans or lines of credit.
4. Property Tax Assessments
Property taxes are based on your home’s assessed value. Knowing your home’s true market value helps you contest overvalued tax assessments and potentially lower your taxes.
5. Insurance Needs
Accurate knowledge of your home’s value ensures you have the right amount of homeowners insurance. Over or under-insuring can lead to higher premiums or insufficient coverage.
How to Determine Your Home’s Value
There are several ways to determine your home’s worth:
1. Online Estimators
Websites like Zillow, Redfin, and Realtor.com use algorithms to estimate your home’s value based on recent sales. While convenient, these estimates may not consider unique home features or recent updates.
2. Comparative Market Analysis (CMA)
A CMA from a local real estate agent compares your home to similar properties that recently sold. This provides a more accurate estimate, considering local market conditions.
3. Professional Appraisal
A professional appraiser evaluates your home’s condition, location, and market factors to provide an accurate valuation. This is the most reliable option, often required for refinancing or loans.
4. Agent’s Opinion
Real estate agents can provide an estimate based on their local knowledge and experience. Many agents offer free home evaluations, especially if you’re thinking of selling.
Key Factors That Affect Home Value
- Location: Proximity to schools, transportation, and amenities boosts value.
- Size and Layout: Larger homes or homes with more functional space are typically valued higher.
- Condition and Age: Well-maintained, updated homes tend to be worth more.
- Market Conditions: A seller’s market typically drives up home prices, while a buyer’s market may lower them.
- Upgrades: Renovations, like updated kitchens or energy-efficient appliances, can increase home value.
How to Maximize Your Home’s Value
- Renovate key areas, such as kitchens or bathrooms.
- Boost curb appeal with landscaping or exterior repairs.
- Add square footage by finishing basements or attics.
- Update systems like HVAC or plumbing.
Conclusion
Knowing your home’s value is essential for making sound financial decisions, whether you’re selling, refinancing, or simply managing your property. By using online tools, getting a Comparative Market Analysis, or hiring a professional appraiser, you can accurately determine your home’s value.
Ready to discover how much your home is worth? Start with an online estimator or consult a local real estate agent today!
by Michael Jiang Suo | Sep 6, 2026 | For Sellers
In today’s competitive real estate market, sellers are seeking ways to stand out and sell quickly. One effective strategy is a pre-listing inspection. While it may seem like an added expense, a pre-listing inspection offers several benefits that can help you sell faster and at a better price. Here’s why it could be worth considering.
What is a Pre-Listing Inspection?
A pre-listing inspection is a home inspection done before your property hits the market. A certified inspector checks the condition of the home and identifies any issues that may need fixing. This report can guide your decisions and help you price your home accurately.
Key Benefits of a Pre-Listing Inspection
1. Accurate Pricing
With a clear understanding of your home’s condition, you can price it more accurately, avoiding overpricing or underpricing.
2. Builds Buyer Confidence
Buyers are more likely to make offers on homes that have already been inspected. This transparency can lead to faster decisions and fewer delays.
3. Faster Closing
Addressing repairs upfront leads to fewer negotiations and potential delays during closing, making the process quicker and smoother.
4. Avoid Price Negotiations
If buyers discover issues during their own inspection, they may ask for price reductions or repairs. A pre-listing inspection helps you avoid these surprises.
5. Improved Negotiation Leverage
Fixing issues ahead of time can give you more power in negotiations, helping you maintain your asking price.
6. Reduces Deal Risks
A pre-inspection minimizes the chances of a sale falling through due to unexpected issues discovered later on.
What’s Covered in a Pre-Listing Inspection?
A pre-listing inspection typically checks:
- Structural Integrity: Foundation, roof, and walls
- Plumbing & Electrical: Functionality and safety
- HVAC & Appliances: Condition and performance
- Exterior/Interior: Windows, doors, and overall condition
Should You Get One?
While the cost of a pre-listing inspection (around $300-$600) can be an investment, the benefits of setting the right price, avoiding surprises, and closing quickly often outweigh the expense. It’s particularly useful in a competitive market, but may not be necessary if your home is newly renovated or in a hot seller’s market.
Conclusion
A pre-listing inspection can provide significant advantages, helping you sell your home faster, with fewer complications, and at a fair price. If you’re considering selling, a pre-listing inspection could be a smart move to streamline the process and increase your chances of success.
